The Architecture Debt Behind PB Fintech's 48% Collapse
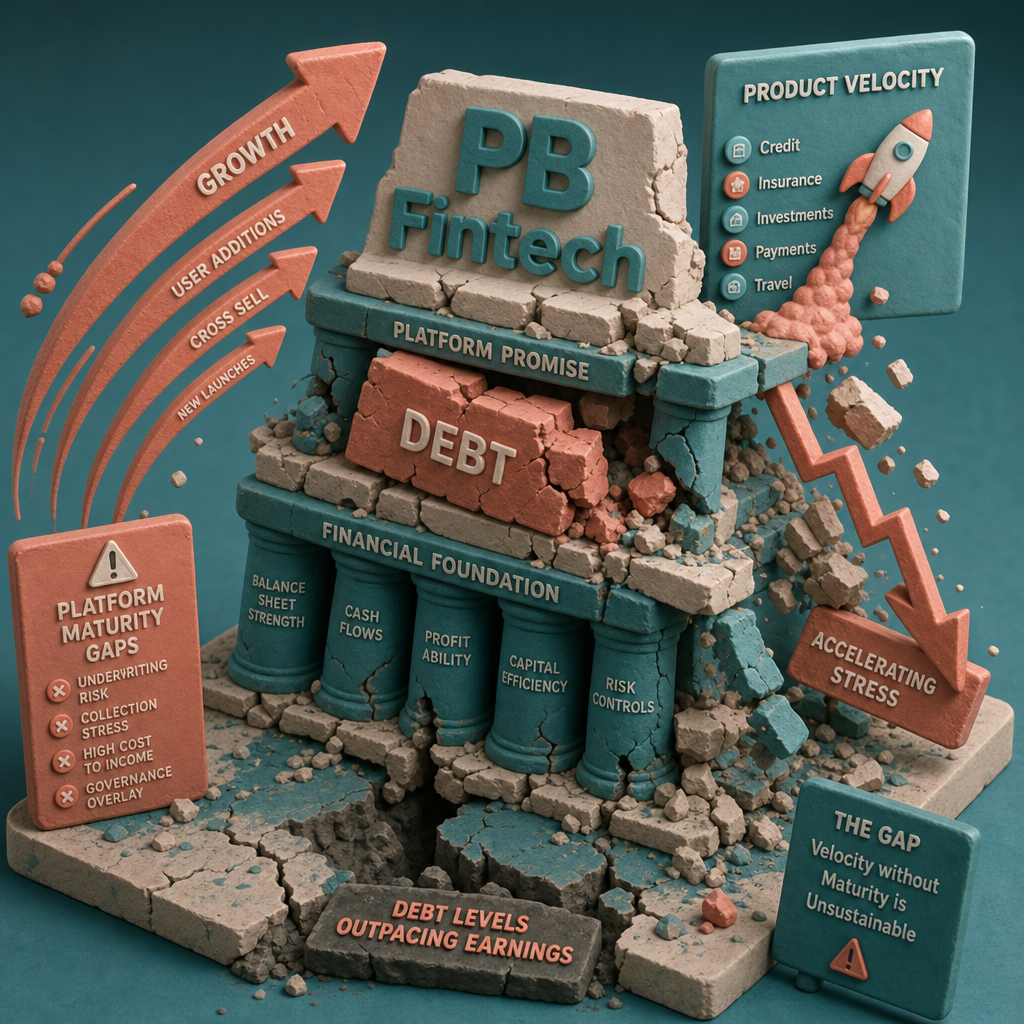
When product velocity outpaces platform maturity, market corrections arrive faster than your migration plan.
PB Fintech, the parent company of Policybazaar and Paisabazaar, lost 48% of its market value in six trading sessions, bringing the stock back to its IPO price. The same week, doctors and insurers sued California's governor over premium increases, Farm Bureau Insurance closed an acquisition in the Mountain West, and digital lenders continued taking share from legacy banks in the personal loan market.
These aren't isolated incidents. They're symptoms of a structural problem in insurance and financial services technology: companies building distribution before they build platforms.
The Pattern Behind the Volatility
PB Fintech's collapse happened alongside steady operational growth in the digital lending sector. According to recent data, digital lenders are outpacing legacy banks in personal loan origination, with younger borrowers increasingly preferring fintech apps over traditional institutions.
The divergence tells you something important about architecture decisions made three to five years ago. Distribution platforms that aggregate third-party products face different technical debt than lenders operating their own underwriting systems. One scales through API connections and comparison engines. The other requires core processing infrastructure, decision engines, and regulatory reporting frameworks.
When market conditions tighten, investors reassess which model generates durable value. A 48% drop in six days suggests the market concluded that aggregation without owned infrastructure creates volatility without defensibility.
Farm Bureau Insurance's acquisition of Mountain West operations represents the opposite approach. Traditional carriers expand through entity consolidation, then face the multi-year challenge of platform integration. The technical complexity is higher upfront, but the moat deepens with each system you successfully merge.
The Premium Equation Nobody Wants to Solve
The lawsuit against California Governor Newsom over health insurance premium increases exposes the tension between regulatory constraints and operational costs. Doctors and insurers are challenging the same premium structures, which means the economics aren't working for either providers or carriers.
This creates a forcing function for architecture leaders. When premium growth is capped but claim costs rise, the only variable you control is operating expense. That puts core systems modernization back on the roadmap, not as a strategic initiative but as a survival requirement.
Insurance carriers running mainframe policy administration systems spend 15-25% more on transaction processing than competitors on modern platforms. In a margin-compressed environment, that gap becomes existential. The carriers who deferred modernization during the low-rate environment now face it during capital constraint.
The regulatory environment in critical infrastructure sectors like healthcare and insurance creates additional complexity. You can't migrate a book of business to a new platform without state approval. You can't run parallel systems indefinitely without doubling your operational cost. The path forward requires coordination between enterprise architecture, legal, actuarial, and state regulators across multiple jurisdictions.
The Trust Tax on Emerging Models
OpenAI experienced two separate safety employee resignations in the same period, with one explicitly stating the company's "culture is broken." OpenAI's CEO Sam Altman separately characterized ascribing religion to AI models as a "safety issue."
The connection to insurance technology isn't immediately obvious until you consider where generative AI is being deployed in underwriting and claims workflows. Carriers are experimenting with large language models for first notice of loss processing, policy document summarization, and automated underwriting recommendations.
When safety researchers leave AI companies citing cultural concerns, it creates reputational risk that flows downstream to enterprise adopters. Regulated industries already face heightened scrutiny on algorithmic decision-making. Adding vendor stability questions on top of model explainability requirements compounds the governance challenge.
When product velocity outpaces platform governance, technical debt converts to market cap erosion faster than your backlog can address it.
This matters for architecture leaders making build-versus-buy decisions on AI capabilities. A SaaS vendor integrating OpenAI models inherits both the technical dependency and the reputational risk. Building in-house requires different skills but provides better control over model provenance and decision audit trails.
The regulatory pressure extends beyond insurance. Banks in the UK saw share prices tumble as gilt yields hit their highest levels since 1998, driven by budget uncertainty. When funding costs spike, institutions reassess every technology investment that doesn't directly reduce operating expense or regulatory risk.
The Fintech Fragmentation Problem
Monzo is courting private equity investors after Nubank walked away from acquisition discussions. OpenPayd is targeting a year-end Nasdaq listing to fund U.S. expansion and acquisitions. Banks are pitching cheaper dollar funding routes to large corporates through domestic bonds.
The pattern shows fragmentation in the fintech infrastructure layer. Digital banks need capital. Payment processors need liquidity for expansion. Traditional banks are competing on funding cost, not product features.
For enterprise architects in insurance and financial services, this creates dependency risk. If your claims payment workflow relies on a fintech vendor that's hunting for acquisition or listing to stay capitalized, you need contingency architecture. The migration plan you don't have becomes the operational risk you can't quantify.
The shift also changes the talent equation. When fintechs consolidate or struggle to raise capital, experienced platform engineers look for stability. Regulated enterprises with modernization budgets can attract talent that wasn't available 18 months ago, but only if they've already committed to platform transformation.
Capital Efficiency as Architecture Constraint
The banks' pitch on cheaper dollar funding through domestic bonds addresses a structural problem for large corporates. When offshore funding costs rise, treasury teams look for alternatives. Banks with domestic deposit bases can offer better rates, but only if their payment and FX infrastructure supports the workflow.
This creates an integration challenge for insurance carriers with international operations. Policy administration systems built for domestic markets often lack the multi-currency and cross-border payment capabilities needed for global books of business. Adding those features to legacy systems is expensive. Replacing the entire platform is riskier.
The alternative is building a financial services integration layer that abstracts payment processing from policy administration. This requires API-first architecture, event-driven data flows, and separation of transaction execution from transaction recording. It's the same pattern that successful fintechs use, but enterprise implementations face different scale and regulatory requirements.
PB Fintech's stock returning to IPO price suggests investors are reassessing which companies built this separation and which ones coupled distribution to third-party infrastructure without ownership of the value chain.
The Roadmap Waiting in Your Backlog
The convergence of these stories points to a specific architecture decision that can't be deferred: separating your customer experience layer from your core processing systems through well-defined domain boundaries.
Companies that built aggregation platforms without owned underwriting infrastructure face market skepticism when growth slows. Carriers suing over premium caps need operating cost reduction that only comes from core system modernization. AI vendors losing safety researchers create governance risk for enterprise adopters. Fintech vendors hunting for capital create dependency risk for their enterprise customers.
The common thread is architectural maturity. Systems with clear domain boundaries, well-defined APIs, and separation between experience and processing can adapt to market shifts faster than monolithic platforms or tightly coupled aggregation layers.
For architecture leaders in regulated industries, the work isn't identifying which technologies to adopt. The work is building the platform foundation that lets you swap technologies without rebuilding your entire value chain.
Start with your payment processing layer. If you can't change payment vendors without modifying your core policy or claims system, you've identified your highest-priority decoupling project. Then look at your data integration patterns. If changing your analytics vendor requires ETL rewrites across six systems, your data architecture is blocking your ability to respond to market conditions.
The carriers who deferred this work during the growth years are now facing it during capital constraint. The aggregators who prioritized customer acquisition over platform ownership are seeing their valuations reset. The architecture decisions you make in the next 18 months will determine whether your company is consolidating market share or getting consolidated.